Swing Trade Ideas – March 12, 2026
Laurie’s Abbreviation Index:
** ‘div’ – dividend
** ‘m/m’ – month over month
** ‘y/y’ – year over year
** ‘Inven’ – inventories
** ‘mfg’ – manufacturing ** +/- – plus or minus, positive or negative
** Underlined text – higher volume premarket
** ‘d’ – day
** ‘Y’ – year
**govt – government
Color Key: Positive – Neutral – Negative
Global Markets: USA, Europe, Japan, China, Hong Kong – slight negative set-up
• Commodities: Gold, Silver, Copper, Palladium, Oil, natgas, AGGS, Bitcoin
• Yields: 30Y Bond -0.30% Currencies: USA$ +0.10% CAD -0.02% YEN +0.12% BTC/USD-0.26% Vix:24.6
•
Events:USA: Reports of tanker attacks in
Persian gulf led to oil higher despite govts release of reserves
Stock News:DKS+4.5% OLLI+0.3% PATH-9% DG-5% Earnings
Equity: USA indices pulled back overnight as tanker attacks in the
Persian gulf led to oil moving higher. Indices bounced in the European session
but are pulling back in the NY premarket trading. MAGs are lower with TSLA
outperforming AVGO lagging. Semis in general are lower and inline with QQQ. 10Y
yield 4.2% has risen sharply and pressuring yield sensitive equities like
staples and small caps which are the weakest group premarket. Financial
weakness is continuing with XLF weakest S&P sector premarket. MOVE rising,
credit spreads widening, private credit index falling and private equity firms slowing
redemptions are signaling rising concerns in the fixed income space which is a
concern for the equity markets with lower quality, highly leveraged companies
more sensitive. XLE is the only positive sector premarket and USA indices are
trading inversely correlated to oil prices which are volatile intraday with
every news item. Fertilizer stocks are leading premarket as the shutdown of the
Hormuz St. impacts world supply and agg commodities are rising as fertilizer
shortages will impact crop yields and some staples stocks are lower as higher
commodity prices increase input cost. IMO the equity market is one big trade on
when and how the Iran war will end and is still pricing in either USA pulls out
soon or Iran collapses soon and even then is pricing in a rapid recovery of the
global oil network. The left tail risk for equity is the conflict dragging out
for many weeks or months. Meanwhile the option market has been supportive with
0DTE put sellers stepping up at the lows. Today would be watching 6720-6700 as
a level where they may step in. IV is high and in most names the options are
leaning into puts which is a setup for sharp bounces (e.g. TSLA Wed) which may
be temporary. Risk is if the put sellers dont step up, which can lead to a
large drawdown with 6500 a potential lower bound.
•
Stock MOS CF USO MEOH GOOGL META NVDA Speculative DKS VG SOFI
Indices /CL SLV XLE UNG US$ KRE IWM XLF ETHE FEZ XBI EFA SMH RSP ARKG ARKK SPY KWEB
S&P500 MOS CF DOW LYB DG CCL LUV MS UAL GPN GNRC
Other DKS XPEV VG PBR SAN NBIS LI STM CRWV MUFG SOFI JOBY
BHP
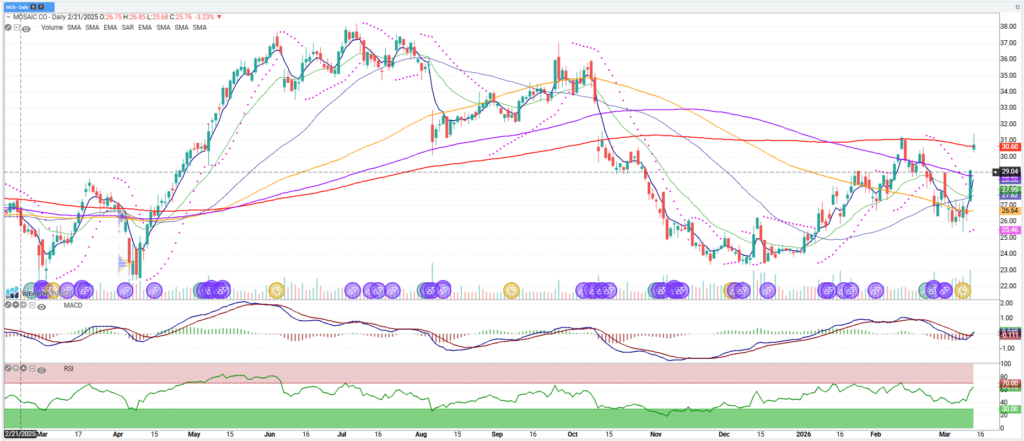
MOS
MOS is a potash supplier which is used for fertilizer. Hormuz closure is affecting world shortage of ammonia based fertilizers which is leading to the fertilizer stocks are moving aggressively higher. CF is a pure play on ammonia and is going parabolic. MOS and NTR are potash based and sympathy plays on the monkeys buying all fertilizer names. Risk is the strait reopening and potential reward is a continuation in the closure of the strait