Swing Trade Ideas – April 10, 2026
Laurie’s Abbreviation Index:
** ‘div’ – dividend
** ‘m/m’ – month over month
** ‘y/y’ – year over year
** ‘Inven’ – inventories
** ‘mfg’ – manufacturing ** +/- – plus or minus, positive or negative
** Underlined text – higher volume premarket
** ‘d’ – day
** ‘Y’ – year
**govt – government
Color Key: Positive – Neutral – Negative
Global Markets: USA, Europe, Japan, China, Hong Kong – positive set-up
• Commodities: Gold, Silver, Copper, Palladium, Oil, natgas, AGGS, Bitcoin
• Yields: 30Y Bond -0.05% Currencies: USA$-0.02% CAD -0.13% YEN -0.13% BTC/USD+0.19% Vix:20.2
•
Events USA: CPI 830ET, UofM 10ET CDN:
employment data 830ET
Stock News: TSM Q1 revenue beat
Equity: Global indices are higher ahead of the dramatic
Iranian-USA ceasefire talks on Saturday in anticipation of Hormuz reopening and
zero impact to the elevated oil prices and shortages of products like sulfur,
fertilizer and helium. SPX is now positioned with positive gamma which reduces
volatility and 0DTE positions at 6800 and 6850 set likely range. War news
continues to move the market and Thurs pop was after a report that Israel would
start talks with Lebanon. Correlation between stocks is declining rapidly and
leading to large dispersion e.g. semi +, software -. Today the leadership
continues to be AI related with optical, memory and semi. MAGS are led by AVGO
and semi higher on TSM Q1 revenue slightly higher than expected but reinforcing
the meme that AI spending with go to infinity and beyond. MRVL is notably
approaching a monthly breakout and example of how the semis remain hot but
names other than NVDA are leading. Bessent is raising concerns regarding cyber
security risks following Anthropic Mythos release and potentially leading to a
bid to names like PANW, CRWD which have been weak along with the software
sector. Banks are reporting earnings next week and may see a bid ahead of the
reports. Foreign markets are recovering despite no actual change to situation
in the middle east with Japan and Europe outperforming USA indices. USA CPI was
lower than median forecast but core 2.6% y/y well above Fed target and impact
of middle east war not fully reflected.
•
Stock META AMZN MRVL XLE NVDA INTC ZS Speculative HMY XPENG
Indices UFO SMH KWEB ARKK ARKX /CL ETHE
XLK EFA UNG USO XLF US$ GLD
S&P500 LITE COHR GLW SNDK CIEN CRH PANW CRWD WDC AMAT NOW ORCL
Other AAOI CRWV MRVL LI ALAB TECK BIDU
LOGI CRCL TSM NET PHG NVO ASML ASTS RKLB NBIS
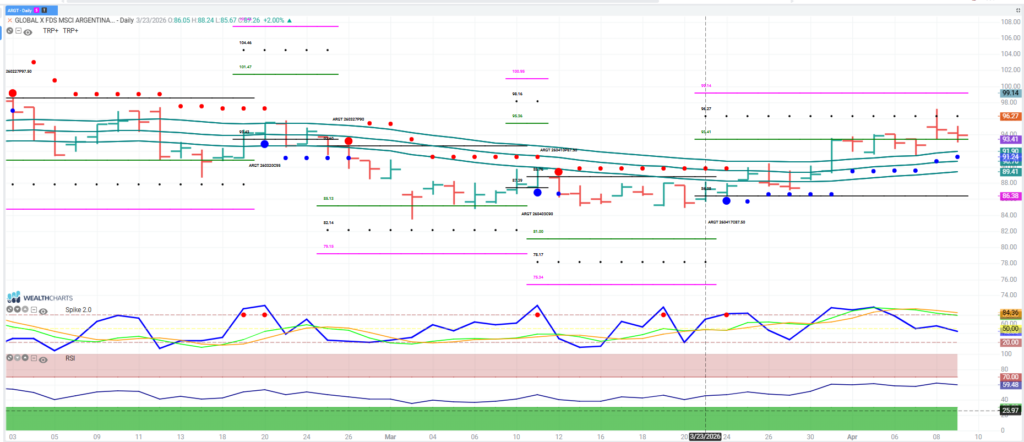
ARGT
Foreign names are improving with a lower US$. ARGT is an Argentinian etf with MELI the AMZN of S America as the largest holding but also a number of energy companies which can benefit if one thinks that energy will be tight for several more months.